Estate-Planning Financial Advisors
Advisors who tell us they work on estate planning — the details they provide, the states they serve, and where to check each one’s public record. Advisors never pay for placement.
What an estate-planning financial advisor actually does
Estate planning is usually thought of as a lawyer’s job — the will, the trust, the powers of attorney. But most of what decides where your money actually goes is financial, not legal: who is named on each retirement account, how your accounts are titled, when and how you give during your lifetime, and how taxes are handled along the way. That is the work an estate-planning-focused financial advisor does, in coordination with the attorney who drafts the documents and the accountant who files the returns.
A good one will not try to be your lawyer. They plan the financial side and tell you plainly when you need an estate attorney instead. If you are starting from the documents, our plain-English guides and trust explainers are a free place to begin.
How to verify an advisor — today, yourself
We will be candid: the listings below are self-reported by the advisors, and we have not yet independently verified them. We are building that verification. Until it is in place, you should confirm anyone before you meet:
- Check FINRA BrokerCheck. Every profile with a CRD number links straight to that advisor’s record at brokercheck.finra.org — registrations, exams passed, and any disclosures.
- Confirm the credentials. A CFP® can be checked with the CFP Board; a CPA with the state board of accountancy. Our editorial standards explain the standard we hold ourselves to.
- Ask how they are paid. Fee-only, fee-based, and commission each create different incentives. The profile shows what the advisor reported; ask them to confirm.
A listing in this directory is not an endorsement, and nothing here is legal, tax, or investment advice.
The directory
3 advisors · 3 with a photo
The details on each card are provided by the advisor and have not been independently verified.
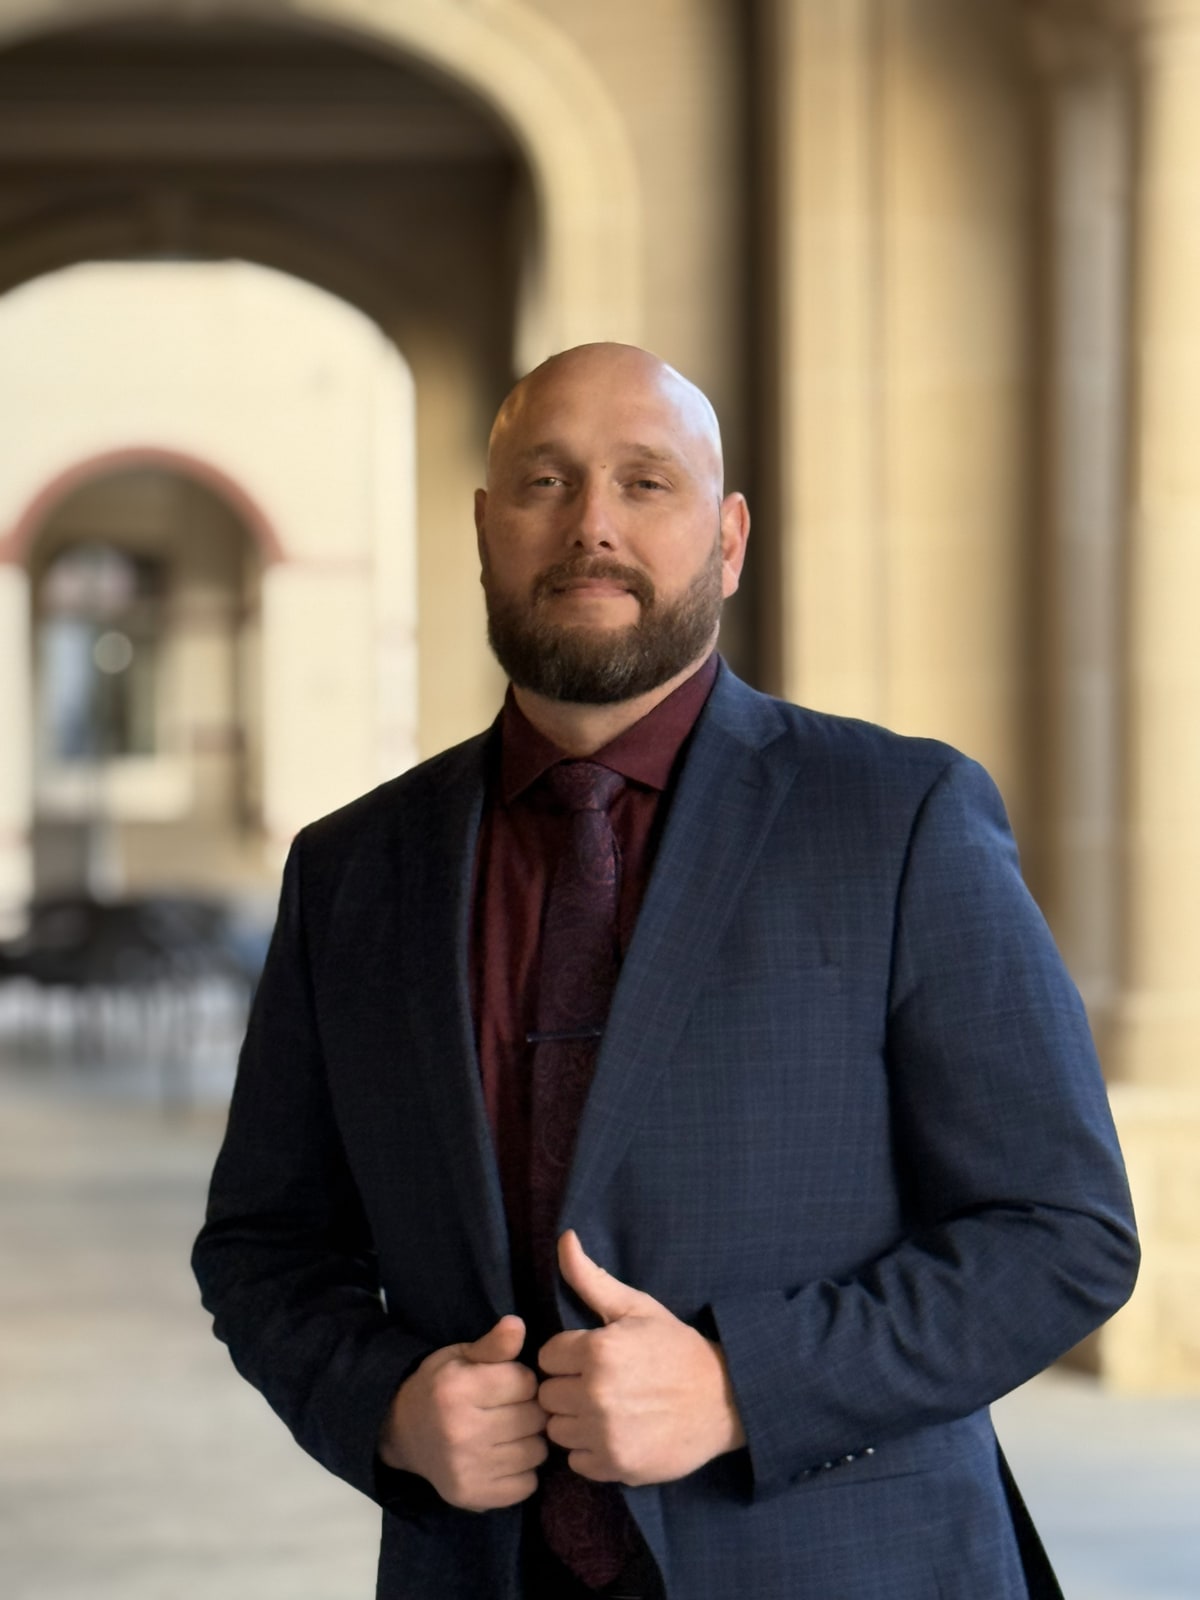
Estate planning · Retirement income planning · Investment management · Tax planning
States served: Texas
Reported CRD #6459499
View profile →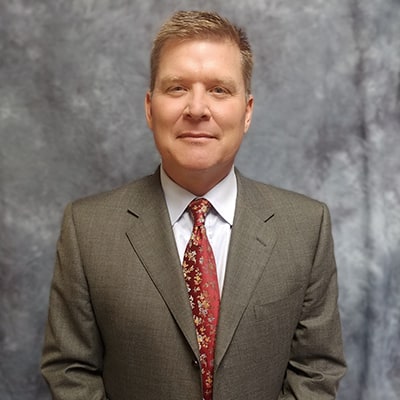
Estate planning · Retirement income planning · Investment management · Tax planning · Trust administration · Business succession & exit planning · Charitable & legacy planning
States served: Florida
Reported CRD #7006846
View profile →
Estate planning · Retirement income planning · Investment management · Tax planning · Business succession & exit planning · Charitable & legacy planning
States served: California
Reported CRD #2985157
View profile →How to choose an estate-planning advisor
The right advisor for an estate is not necessarily the one with the most letters after their name. A short checklist:
- Do they actually do estate work? Plenty of advisors will say yes. Ask for specifics: trusts they coordinate on, how they handle beneficiary reviews, whether they work with your attorney.
- How are they paid, exactly? Get it in writing. Ask whether they earn commissions on anything they might recommend.
- Will they put it in writing? A fiduciary standard, a clear fee, and a written plan are reasonable to expect.
- Talk to more than one. There is no cost to sending a request here, and no obligation. Compare.
Common questions
What does an estate-planning financial advisor do?
An estate-planning-focused financial advisor helps you organize how your money and property pass to the people and causes you choose — coordinating beneficiary designations, account titling, tax-aware gifting, and charitable plans, and working alongside the attorney who drafts your will or trust. They plan the financial side; they do not, by themselves, practice law.
Do advisors pay to be listed in this directory?
No. Advisors never pay for placement. Advisors appear in alphabetical order by name, never by payment or by anything they report about themselves.
Have you verified these advisors' credentials?
Not yet. The listings are self-reported by the advisors. We are building independent verification; in the meantime a profile with a reported CRD number links to FINRA BrokerCheck, and an insurance producer's license can be looked up with the state insurance department, so you can check the record yourself before you talk to anyone. A listing here is not an endorsement.
Does it cost anything to contact an advisor?
No. Sending a request through a profile is free and carries no obligation. Your request is matched to an advisor by the ZIP code you give, and that advisor reaches out to you; it may not be the advisor whose profile you were viewing.
How do I choose the right advisor?
Check their record on BrokerCheck, ask how they are paid (fee-only, fee-based, or commission), confirm they routinely handle estate and legacy work, and make sure they will coordinate with your estate attorney and tax preparer. Talk to more than one before deciding.
Where this data comes from
Advisor listings are self-reported profiles published through AdvisorWorld. This directory uses version v3, published November 15, 2026. We show what an advisor provides as they provided it, leaving out only entries outside this site’s subject (annuity products).
Advisors are listed free and never pay for placement. Advisors appear alphabetically by name. A listing is not an endorsement, and we have not yet independently verified these credentials — see our editorial standards.